Quick Summary
Small businesses waste hours on scattered invoices, manual approvals, and disconnected finance systems. Real automation removes operational drag by fixing broken workflows first, then automating what matters most, saving time and cutting errors permanently.
Introduction: Where Finance Overhead Actually Lives
Your finance team is probably not spending time on complex analysis. They're spending it waiting.
Waiting for invoices that arrived three days ago but nobody uploaded yet. Waiting for a manager's approval that's sitting in someone's email inbox. Waiting for the same vendor data to be entered into three different systems because nothing talks to each other.
This is not a hiring problem. This is not a software problem. This is a workflow problem.
Small business founders don't see finance overhead when it starts. It looks like one person manually checking invoices twice because the system didn't catch it the first time. One manager approved payments at 9 PM because the request came late. One spreadsheet created "just for now" that somehow became your reconciliation system two years later.
But here's what happens: those small delays compound. Your finance team spends 40% of their time chasing paperwork, fixing duplicate entries, and rebuilding reports that should be automatic. Your business owner makes cash flow decisions three days late because reports take time to pull together manually. Your AP team codes 200 invoices monthly but catches errors in week three when it's too late to fix vendor records.
This is finance overhead. Not the cost of salaries or software. The hidden cost of broken processes.
Finance Overhead Usually Starts Small
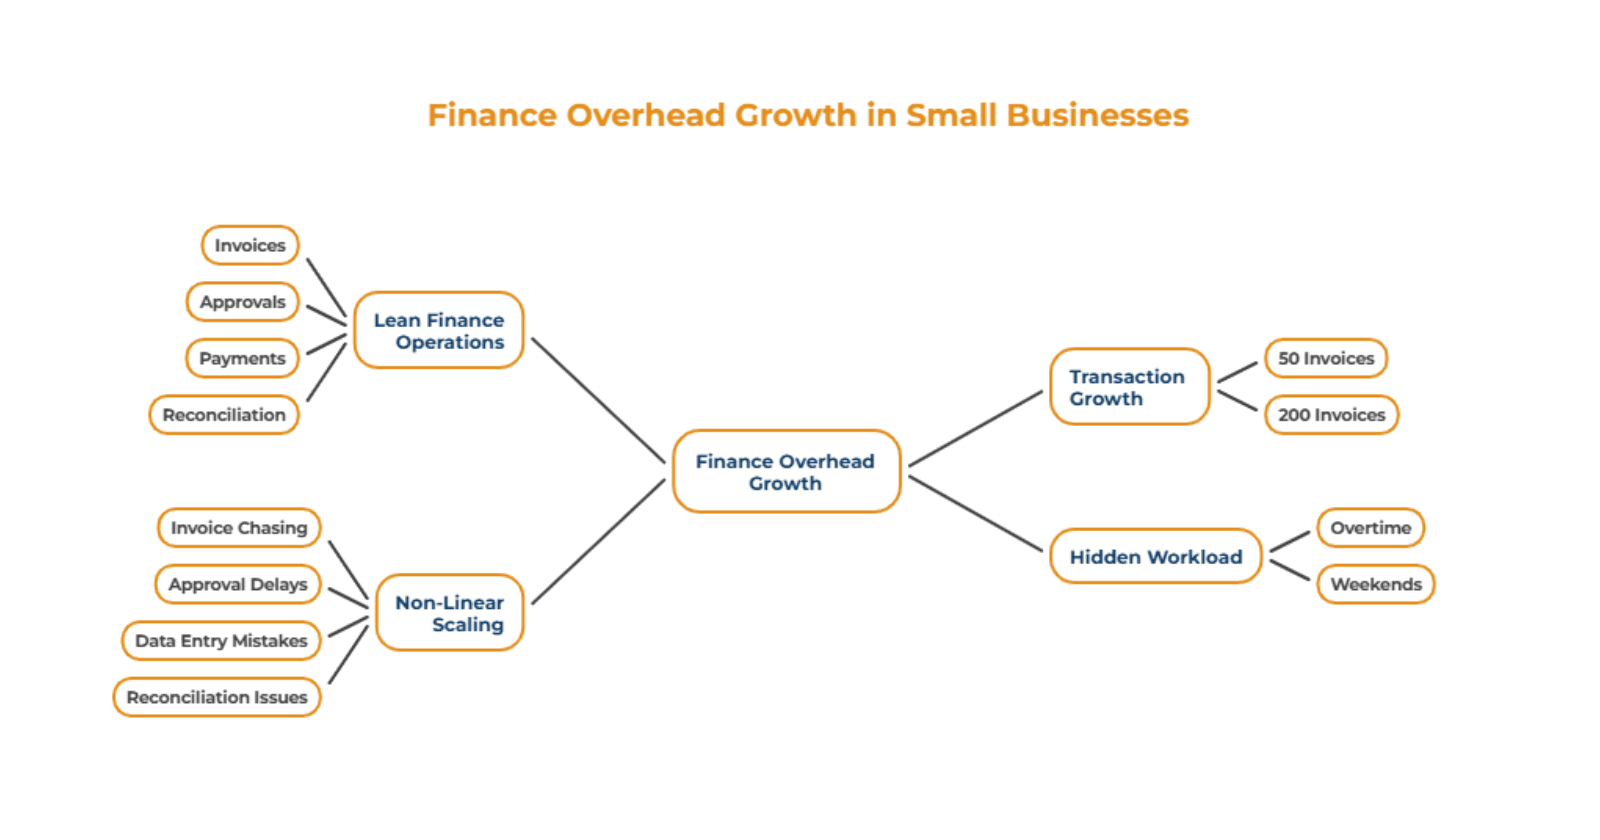
Every small business runs on lean finance operations. One or two people handling invoices, approvals, payments, and reconciliation. That works fine when you're processing 50 invoices monthly. It breaks at 200.
The problem is that manual finance work doesn't scale linearly. If you double your transactions, you don't double your processing time, you triple it. Because now there's more invoice chasing, more approval delays, more data entry mistakes that need correcting, and more time spent trying to reconcile numbers that don't match.
Most small business leaders don't realize this is happening until someone in finance quits. Then suddenly the workload is visible, it was always there, just hidden in overtime and weekends.
Why Finance Teams Become Overloaded as Businesses Grow
Growth should feel like progress. In finance, it often feels like collapse.
Your sales team brings in 3x more customers. That means 3x more invoices. Your vendor network expands. That means invoices coming from different systems, different formats, different approval chains. Your payroll doubles. That means more expense reimbursements, more tax complications, more reconciliation work.
But your finance headcount? Usually it stays the same.
This is where businesses make a mistake: they hire another finance person instead of removing the work that never should have been manual. One more person doesn't fix the problem if the problem is broken workflows. It just distributes the broken workflow across two people.
Finance Tasks Small Businesses Should Automate First
Not all finance work deserves automation. Some should never be automated until your processes are clear. But these tasks create immediate overhead and automate well:
Invoice capture and coding.
Manually typing invoice data is your biggest time sinkhole. A system that captures invoice details automatically (using receipt scanning or email forwarding) reduces data entry by 80%. Better: if your system learns which vendor category each invoice belongs to, coding errors drop dramatically.
Approval routing.
Stop invoices getting stuck in email. Automated approval workflows route invoices to the right person based on amount, vendor, or department. No more "I didn't see that email" delays.
Expense reimbursement.
Employees submit expenses. Managers approve of them. Finance codes them. They get paid. In automated systems, this takes 5 days. In most small businesses, it takes 3-4 weeks because expenses sit in spreadsheets waiting for someone to process them.
Recurring payments.
Rent, subscriptions, utilities these get paid the same amount every month. Stop manually entering them. Automate the payment creation and just review before processing.
Payment reminders and reconciliation.
When an invoice is 10 days from due, it should flag automatically. When you receive a payment, it should match to the right invoice automatically, not require 15 minutes of manual hunting.
Month-end reporting.
If your finance team spends Friday afternoon pulling reports from three systems and rebuilding numbers in a spreadsheet, you have a reporting problem. Your accounting system should generate standard reports in one place.
How Automation Reduces Invoice and Approval Delays
Manual invoices move slowly by nature. An invoice arrives. Someone opens it. Someone else retrieves the purchase order to verify amounts. A manager approves it. Finance codes it. Then it gets paid. In small businesses, this takes 10-14 days.
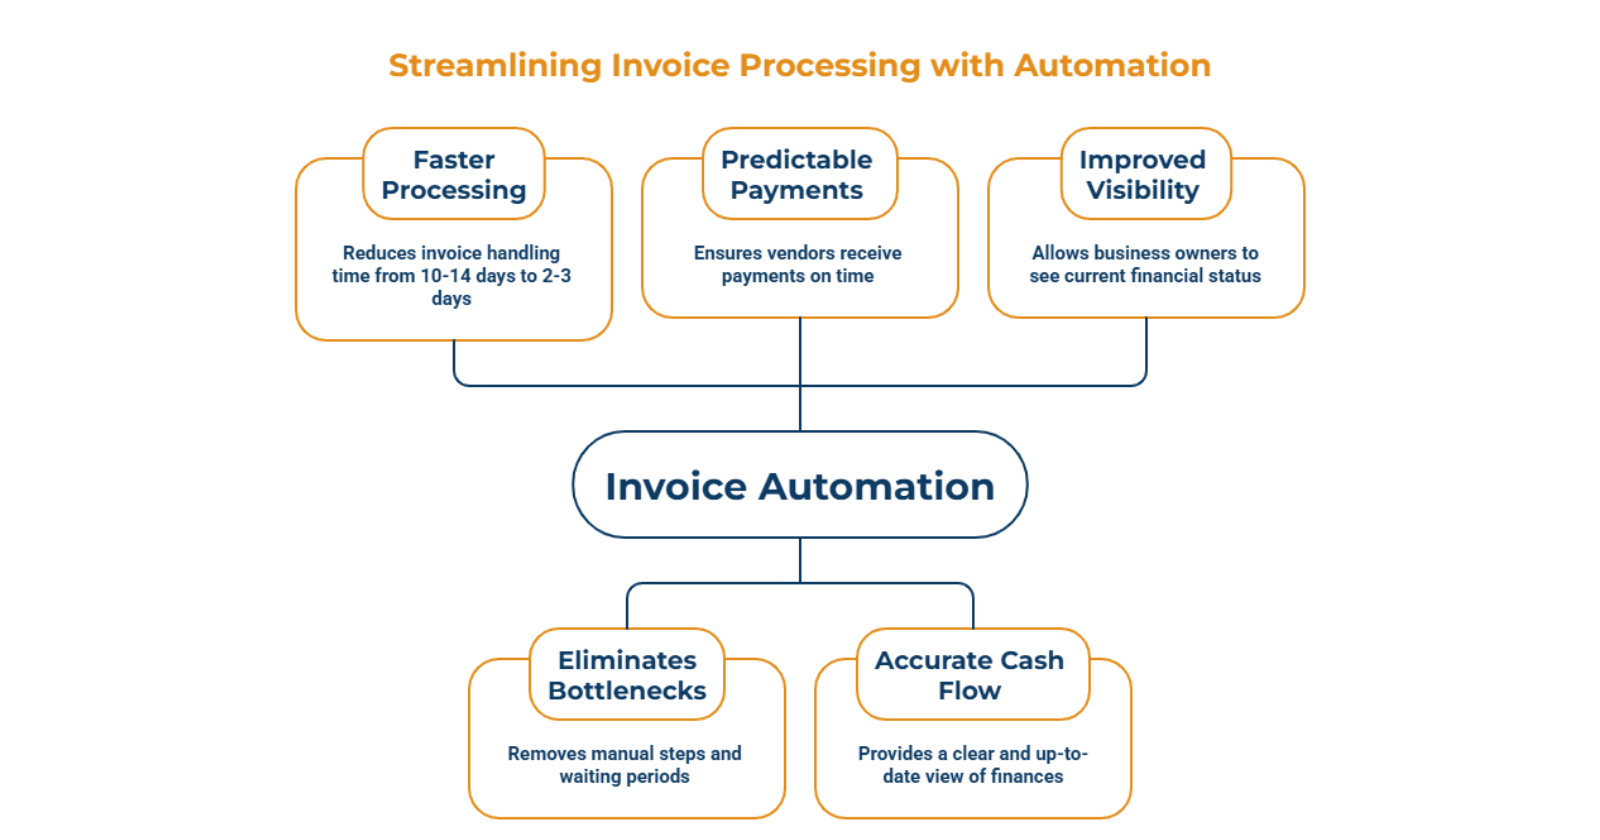
Automated invoice workflows compress this to 2-3 days. Why? Because every step happens without waiting.
Invoice arrives → system captures details automatically → system verifies it matches the purchase order → system routes to the right approver → approver reviews and clicks approve → payment processes automatically.
No emails asking "did you see this?" No invoices sitting in someone's inbox. No approval delays because someone was busy.
The real benefit isn't just speed. It's predictable. Your vendors know when they get paid. Your cash flow is accurate. Your business owner can see what's due today, not guess based on a spreadsheet from yesterday.
Why Reporting Problems Create More Overhead Than Businesses Realize
Your finance team probably spends one full day every month rebuilding the same reports. That shouldn't happen.
A business owner wants to know this week's cash position. Finance pulls data from the accounting system. But the accounting system doesn't include outstanding expenses from the expense spreadsheet. Or pending invoices that haven't been entered yet. Or payments that cleared the bank but haven't been coded.
So finance manually combines data from three sources, corrects errors, and delivers a report that's 3 days old by the time it arrives.
Automated reporting connects these systems. One dashboard shows real cash position: money in the bank, money pending from customers, money going out to vendors, money committed for payroll. It updates automatically. The business owner sees it immediately.
This doesn't just save time. It changes decision-making. Suddenly the owner knows if they can hire this month. They see if a vendor is delaying payments by 30 days. They catch seasonal cash crunches before they happen.
Automation Without Process Clarity Creates New Problems
Here's where most small businesses fail with finance automation: they buy tools before they understand their workflows.
They implement an AP automation system and discover their vendor data is inconsistent (same vendor entered 47 different ways). They launch an expense system and realize nobody actually follows the approval rules (senior people approve their own expenses). They deploy automated reporting and find that nobody trusts the numbers (because the system wasn't reconciling properly).
Automation fails here because it forces clarity. If your processes are broken, automation just makes broken processes faster and more visible.
Fix your processes first. Clarify your approval rules. Standardize your vendor data. Get your accounting system accurate. Then automate those clear processes.
A Practical Finance Automation Roadmap for Small Businesses
Start here. This actually works because it respects reality:
Week 1-2: Map your current finance workflow.
- Where does an invoice come in?
- How many people touch it?
- Where does it get delayed?
- Where are mistakes made?
Document this. Don't guess.
Week 3-4: Identify your biggest pain point.
- Is it invoice delays?
- Approval bottlenecks?
- Reporting delays?
- Month-end closing taking too long?
Fix the biggest one first, not everything at once.
Week 5-6: Fix the process before automating.
If invoices are delayed because approval rules aren't clear, clarify those rules. If data is inconsistent, standardize it. If vendor records are messy, clean them. Automation on top of broken processes just amplifies the problems.
Week 7+: Automate one workflow completely.
Choose one thing: invoice processing. Or expense approvals. Or payment matching. Do that one thing well. Measure the results (time saved, errors reduced, reporting speed improved).
Month 2+: Connect systems.
Once one workflow works, connect it to your other systems. Invoices flow into accounting. Expenses tie to cost codes. Payments match to records automatically.
What Smart Businesses Measure After Automation
You've implemented automation. How do you know it actually works?
Measure these:
- time to process an invoice (target: 2-3 days instead of 10-14).
- Invoice error rate (target: below 0.5%).
- Approval bottlenecks (zero invoices stuck waiting for approval).
- Time your finance team spends on data entry (should drop 70%+).
- Month-end close time (should reduce by 30-50%).
If these numbers don't improve, your automation isn't solving the real problem. Usually, this means the workflow itself still needs fixing.
Conclusion: Finance Automation Is About Control, Not Just Speed
Finance overhead happens when small businesses grow faster than their finance processes can handle. It's not a problem you hire away. It's a problem you eliminate by understanding your workflows, fixing what's broken, then automating what's clear.
The goal is not to add more tools to your already-complex finance stack. The goal is to remove the manual work that steals your team's time and creates errors that compound.
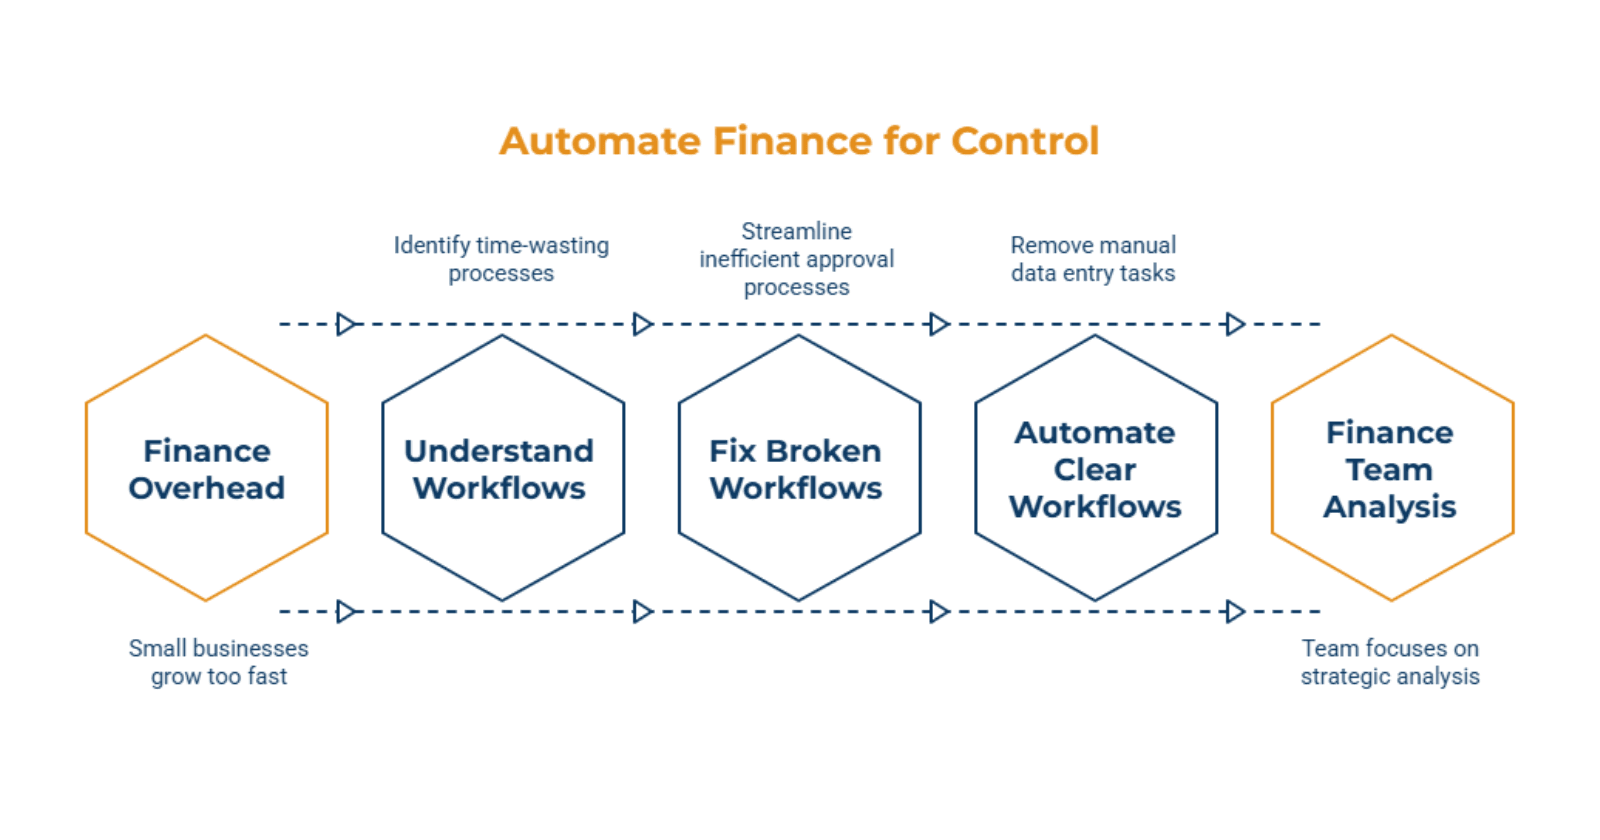
When you automate the right things in the right order, something shifts: your finance team moves from chasing paperwork to actually doing analysis. Your business owner gets accurate cash flow numbers on time. Your vendor relationships improve because payments are predictable.
At Gyan Solutions, we help small businesses achieve this clarity. We start by understanding your specific finance operations where time gets wasted, where errors happen, where approvals get stuck. Then we help you fix those workflows and automate them properly.
The best finance automation isn't flashy. It's invisible. Your invoices process smoothly. Your approvals move on time. Your reports are ready when you need them. Your team has space to do work that actually requires thinking instead of chasing numbers.
Let's start with a diagnosis. Understanding your finance overhead is the first step. Talk to our team about how we help small businesses eliminate operational drag.
FAQs
Q1: What is finance overhead in a small business?
Finance overhead includes all the time, cost, and effort spent on manual tasks like processing invoices, routing approvals, matching payments, entering data repeatedly, reconciling accounts, rebuilding reports, and following up on delayed paperwork.
Q2: How does automation reduce finance overhead?
Automation removes repeated manual work by capturing invoice data automatically, routing approvals without email delays, matching payments to invoices without human intervention, creating reports that update instantly, and keeping finance data synchronized across systems eliminating the need to enter the same information multiple times.
Q3: What finance tasks should small businesses automate first?
Start with invoice capture and coding (biggest time-saver), approval routing (speeds up payment processing), expense reimbursement (reduces processing delays), recurring payments (eliminates manual entry), payment reconciliation (removes matching work), and month-end reporting (saves full days of rebuilding).
Q4: Can finance automation help small businesses improve cash flow?
Yes. Automation creates real-time visibility into outstanding invoices, overdue payments, upcoming bills, and approval bottlenecks allowing business owners to see actual cash position instead of guessing from delayed spreadsheets, enabling faster decision-making and proactive cash management.
Q5: Is finance automation only for large companies?
No. Small businesses often see faster returns from automation because their lean finance teams spend disproportionately more time on manual work, follow-ups, and spreadsheet-based reporting automation eliminates this wasted time immediately.
PAUL LUCKI
I'm Paul Lucki, Head of Business Development at Gyan Solutions. With 9+ years in business automation and ERP implementation, I help leaders eliminate operational silos through integrated systems and real-time reporting that drive competitive advantage